Would you dare drive a car with your eyes closed? Because that's how you're managing your new business's cash flow.
Without an up-to-date cash flow, you're running your business blind. See the 7 commandments that will keep your company from going under.
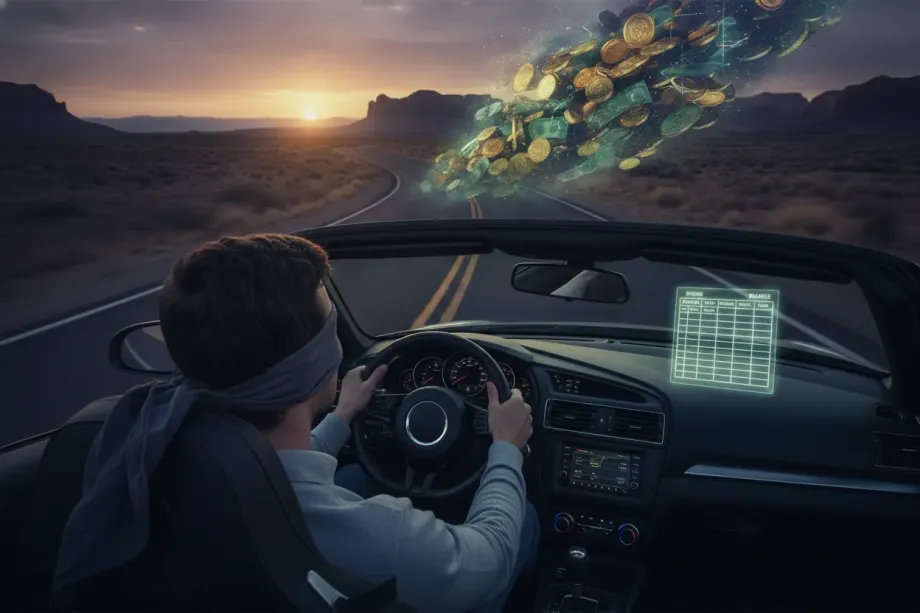
"Would you dare drive a car with your eyes closed? Without a daily updated cash flow, you can't see the road ahead to keep your accounts in the black." - This line made a strong impression at my talk at the Vivamente 2026 conference and left many people shaken — but it's the harsh reality facing new ventures!
Cash flow is the heartbeat of your business and must be measured every single day. Otherwise, the patient might have a "cardiac arrest"!
And here is what I've learned in over 25 years as a statutory financial officer:
- Accrual vs. Cash: you may have booked $1 million in revenue (accrual basis) and have $0 in the bank. That's where businesses collapse. It's essential to monitor your receivables and align them with your payment schedule and debt obligations.
- WACC — Weighted Average Cost of Capital: this is the minimum return your investment must generate. If it doesn't exceed your opportunity cost, you're losing your own money — or that of the shareholder you represent.
- Capital Structure: The ratio between investor equity and third-party debt. It's important to have a clear capital structure strategy and ensure funds are available for revenue-generating investments and working capital.
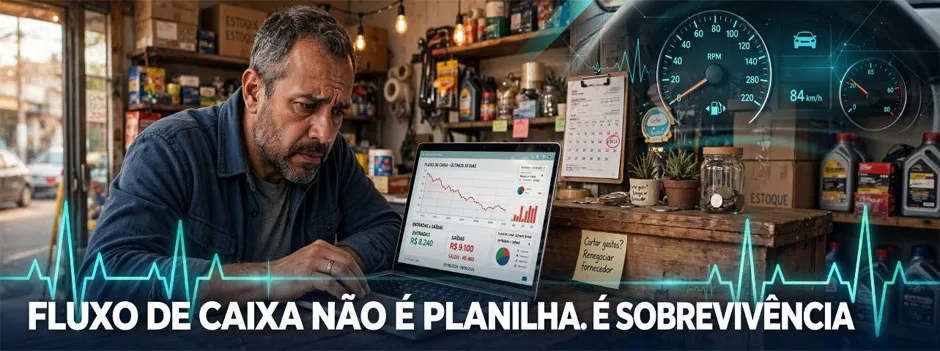
The 7 commandments worth implementing to ensure your company runs properly:
- Record and categorize EVERYTHING. There are no "miscellaneous expenses." Fixed assets vs. consumables. Approval authority from day one.
- Check daily, meet weekly. Actual vs. budgeted. Why did it deviate? How much revenue did we leave on the table per operation? Is it a one-off or a structural issue?
- Inventory is money that earns no interest. What is your inventory worth today? What are your minimum and maximum levels? Pharmacies and fashion businesses often fail right here.
- Don't just fight fires. Think long-term. Keep reserves + pre-approved credit lines even if costly + insurance. Transfer risk.
- Working capital is your financial health reserve. If it's low, you have margin issues or high costs. If it's high, it's time to invest.
- Monitor who owes you money. Clear credit policy. Who deserves credit? Share blacklists with peers (in compliance with regulations).
- Monitor critical suppliers. Extending your average supplier payment terms improves liquidity. Negotiate with guarantees: letters of credit, surety bonds.
A well-crafted plan doesn't guarantee 100% success, but it does ensure at least 80% accuracy.